
An aleatory contract is a legally binding agreement where the obligations and benefits depend on uncertain future events. The outcomes for one or both parties are contingent upon the occurrence of specific events, such as insurance policies or gambling contracts, where the risk of gain or loss is central.
Two features separate an aleatory contract from an ordinary commercial agreement: the triggering event sits outside the control of either party, and the value each side receives is deliberately unequal.
Aleatory contracts rely on chance or unpredictable events, making the obligations or benefits uncertain at the agreement’s inception. This uncertainty distinguishes aleatory contracts from other types of contracts where terms and obligations are typically fixed and clear.
By understanding aleatory contracts, we gain insight into how legal agreements can effectively manage and distribute risk, ensuring that parties are prepared for a range of possible outcomes.
Nature of Aleatory Contracts
The word aleatory derives from the Latin alea, meaning dice. The term entered legal use to describe agreements whose outcome turns on chance rather than on the settled intentions of the parties.
The concept of aleatory contracts has deep roots in Roman law, where they were developed to address transactions involving significant uncertainty and risk.
Roman legal scholars recognised the need for agreements that could account for unpredictable events, leading to the creation of contracts that hinged on the occurrence of specific future incidents.
This historical foundation allowed for the management of risk in a structured legal framework, influencing the development of modern aleatory contracts in areas such as insurance and gambling.
The defining features of aleatory contracts include reliance on chance and uncertainty, with performance or benefits contingent on an uncertain event. Key aspects are dependence on uncertainty, unequal outcomes, and inherent risk.
For instance, an insurance contract is aleatory because the insurer’s obligation to pay depends on the occurrence of an insured event, like an accident or natural disaster.
In contrast to aleatory contracts, commutative contracts involve predictable and quantifiable exchanges, where the terms and obligations are clearly defined and evenly distributed. These contracts are characterised by a balance of value exchanged between the parties.
For example, a sales contract for goods is commutative, as the buyer and seller know their respective obligations and benefits. The primary difference lies in risk allocation: commutative contracts minimise uncertainty, while aleatory contracts embrace it, distributing risk based on the occurrence of specified events.
The difference between an aleatory contract and a contingent contract is control and equivalence. A contingent contract depends on an event a party may influence, with a broadly balanced exchange. An aleatory contract depends on an event neither side controls, and the exchange is unequal by design.
Key Elements of Aleatory Contracts
Aleatory contracts are defined by specific elements that distinguish them from other types of agreements. These essential components include uncertain events, risk allocation, an unequal exchange of value, the parties involved, mutual consent, and legal enforceability.
Uncertain Events
In the context of aleatory contracts, an uncertain event is a future occurrence that cannot be predicted with certainty. The occurrence or non-occurrence of this event determines the performance or benefits of the contract.
The event must also sit outside the control of both parties. An outcome one side can bring about or prevent is a condition, not an aleatory trigger, and courts treat a manufactured event as bad faith rather than chance.
Examples of uncertain events span various industries. In insurance, a car accident or a house fire are uncertain events. In the gambling industry, the outcome of a horse race or a lottery draw constitutes an uncertain event.
Risk Allocation
Risk allocation in aleatory contracts involves distributing the potential for gain or loss between the parties based on the uncertain event. One party, typically the insurer in an insurance contract, assumes the risk of the uncertain event occurring, while the other party, the insured, pays a premium for this risk coverage.
The importance of risk allocation lies in its ability to provide financial protection and stability. By clearly defining who bears the risk, these contracts help manage uncertainty and offer peace of mind to the parties involved.
Unequal Exchange of Value
An unequal exchange of value is the feature that most clearly marks an aleatory contract. One party may pay for years and receive nothing, while another pays once and recovers many times the premium.
This imbalance does not affect validity. Consideration requires that each side gives something of value, not that the values match, so courts enforce the bargain as written even where the payout is wildly disproportionate to the premium.
The Parties Involved
Typical parties in aleatory contracts include the risk bearer and the party seeking protection or potential gain. In insurance contracts, the insurer assumes the risk, while the insured seeks coverage. In gambling, the bettor is the party seeking potential gain, while the bookmaker or casino bears the risk.
Their roles and responsibilities are clearly defined: the insurer or bookmaker provides a promise of compensation or payout contingent on the uncertain event, while the insured or bettor agrees to pay a premium or wager in exchange for this promise.
Consent and Mutual Agreement
Consent and mutual agreement are fundamental for the validity of aleatory contracts. Both parties must willingly enter into the contract, fully understanding the risks and benefits involved. This mutual consent ensures that the agreement is fair and legally binding.
Consent is obtained through a clear and transparent process, often involving written documentation and signatures. This formal agreement process helps to prevent disputes and ensures that both parties are aware of and agree to the terms and conditions.
Legality and Enforceability
For aleatory contracts to be enforceable, they must meet specific legal requirements. These include the contract being made for a lawful purpose, mutual consent, and consideration. The terms must also be clear and unambiguous.
Jurisdictional variations can affect the enforcement of these contracts. Different regions may have specific regulations and legal standards that must be met.

Types of Aleatory Contracts
The types of aleatory contracts include insurance contracts, which compensate for losses upon certain events; gambling contracts, where parties bet on uncertain outcomes; and annuity contracts, providing periodic payments contingent on survival.
Derivatives like options and futures in financial markets also fall under this category.
Insurance Contracts
Insurance contracts are classic aleatory agreements offering financial protection against unpredictable events. For a premium, the insurer compensates the insured for specific losses or damages. The insurer’s obligation to pay depends on the occurrence of specified uncertain events like accidents or disasters.
The primary function of insurance contracts is risk transfer and management. By pooling the premiums paid by many insured individuals, insurers can distribute the risk of significant financial loss across a larger group, making it more manageable.
This system ensures that individuals and businesses can protect themselves against potentially catastrophic financial impacts, providing peace of mind and financial stability.
Different types of insurance serve various needs and cover a wide range of risks.
Health insurance, for instance, covers medical expenses incurred due to illness or injury, ensuring that individuals can afford necessary medical care.
Car insurance covers damages to vehicles and liabilities arising from accidents, protecting drivers from substantial repair costs and legal liabilities.
Business interruption insurance provides financial support to businesses that suffer losses due to unforeseen disruptions, such as natural disasters or fires, helping them to recover and continue operations.
Long-term disability insurance offers income protection to individuals who become unable to work due to a disabling condition, ensuring financial stability during periods of disability.
Homeowner insurance covers damage to a home and its contents due to events like fire, theft, or natural disasters, providing financial support for repairs and replacements.
Each of these insurance types is designed with specific coverage criteria and conditions tailored to the risks associated with different aspects of life and business, exemplifying the versatile application of aleatory contracts in managing uncertainty.
Gambling and Betting Agreements
Gambling and betting agreements are classic examples of aleatory contracts, where the outcome and potential benefits hinge entirely on uncertain future events.
In these agreements, one party wagers money on a particular outcome, such as the result of a sporting event or a roll of the dice, while the other party, typically the bookmaker or casino, agrees to pay out a predetermined amount if the wagered event occurs.
The essential characteristic of these contracts is their dependency on chance, with the risk of loss or gain entirely contingent upon the outcome of the bet, making the contractual obligations highly unpredictable.
Legal and regulatory considerations play a significant role in gambling and betting agreements. These contracts are subject to stringent regulations to ensure fairness, transparency, and the protection of participants.
Different jurisdictions have varying laws governing gambling activities, ranging from outright prohibition to regulated legal frameworks.
For instance, in many countries, gambling operators must obtain licences and adhere to strict guidelines to prevent fraud, money laundering, and other illicit activities.
Regulations also often include measures to promote responsible gambling, such as limits on betting amounts and mandatory self-exclusion programmes for individuals at risk of gambling addiction.
These legal frameworks are crucial in maintaining the integrity of gambling and betting agreements as legitimate forms of aleatory contracts.
Annuities and Retirement Accounts
Annuities and retirement accounts are financial instruments that function as aleatory contracts by providing periodic payments contingent on certain future events, typically related to the lifespan of the retiree.
In an annuity contract, an individual pays a lump sum or series of payments to an insurer, which then provides regular disbursements either immediately or later. These payments continue for a set period or the individual’s lifetime, making the contract’s value dependent on the individual’s longevity.
Annuities and retirement accounts provide guaranteed income, ensuring financial security in retirement and managing longevity risk. They offer tax-deferred growth but may yield lower returns due to fees and conservative payouts.
Risks include inflexibility, early withdrawal penalties, and reliance on the insurer’s solvency, balancing security and risk.
Investment and Financial Instruments (Guarantees)
Investment products like options, futures, and certain bonds are aleatory contracts relying on uncertain future events. Options and futures involve buying or selling assets at set prices on future dates, depending on market movements.
Convertible bonds depend on future stock prices or interest rates. These instruments manage risk and speculation, with potential for significant gains or losses.
The inherent risks and potential rewards involved in these investment products stem from their speculative nature and dependency on market conditions. The primary risk is market volatility, which can lead to substantial financial loss if the market moves unfavourably.
However, these instruments also offer high potential rewards, such as the ability to hedge against market fluctuations or to achieve significant returns through strategic speculation. The use of borrowed capital in many of these contracts can amplify both gains and losses.
Investors must carefully evaluate these factors, balancing the potential for high returns against the risks of significant financial exposure.
Guarantees and surety bonds belong to the same family of financial contracts. A guarantor promises to answer for another party’s default, an event that may never occur, so the guarantor’s exposure rests entirely on someone else’s failure to perform.
Demand guarantees, personal guarantees, and performance bonds all follow the same pattern: a commitment given now against a contingency that may cost the guarantor nothing or a great deal.
Enforceability and Regulatory Compliance
Aleatory contracts are indeed enforceable, provided they meet the essential elements of a valid contract. These contracts, like any other, must adhere to the fundamental principles of contract law to be considered legally binding.
The enforceability of aleatory contracts hinges on the essential elements of a contract, including offer, acceptance, awareness, capacity, legality, and consideration. When these elements are present, courts typically uphold the agreements, even when the outcomes are uncertain or dependent on future events.
To ensure enforceability, aleatory contracts must first include a clear offer and acceptance. The offer must specify the terms of the agreement, and the acceptance must be unequivocal, indicating that both parties consent to the same terms.
Awareness, or mutual assent, requires that both parties understand and agree to the contract’s terms, which is especially critical in aleatory contracts where the implications of the agreement might not be immediately clear.
Capacity ensures that both parties are legally capable of entering into the contract, meaning they are of sound mind and of legal age. Legality requires that the contract’s purpose and terms comply with the law.
Consideration is a crucial element in the enforceability of aleatory contracts. Consideration refers to the value exchanged between the parties, which can be in the form of services, property, or risk management.
In the context of aleatory contracts, consideration might seem unequal due to the contingent nature of the benefits or obligations. However, as long as there is a mutual exchange of value, the consideration is deemed sufficient.
For example, in an insurance contract, the insured pays premiums (consideration) in exchange for the insurer’s promise to cover specific losses or damages (consideration) if an uncertain event occurs. In gambling agreements, the wager placed by the bettor and the potential payout from the bookmaker constitute consideration.
Despite the apparent inequality in the exchange of consideration in aleatory contracts, it remains sufficient for enforceability. The key is that both parties agree to the terms and understand the risks and potential rewards involved.
Courts recognise that the risk assumed by one party and the premium or wager provided by the other party constitute valid consideration, thereby upholding the validity of these contracts.
Various laws and regulations ensure aleatory contracts are fair and transparent. Regulatory bodies like insurance commissions and gambling authorities oversee these agreements. Insurance companies must comply with consumer protection, solvency, and fair practice regulations.
Gambling contracts are regulated to prevent fraud, promote responsible gambling, and ensure operators are licensed and legal. These frameworks maintain the integrity of aleatory contracts, providing legal protection and ensuring lawful, ethical execution.
Enforceability Across Jurisdictions
Enforceability of aleatory contracts varies by jurisdiction, and the sharpest divergence sits with gambling debts rather than insurance. Insurance and annuity contracts bind in all three markets below; wagers do not.
Under UK common law, aleatory contracts are enforceable once offer, acceptance, consideration, capacity, and lawful purpose are satisfied. Section 335 of the Gambling Act 2005 removed the long-standing bar on enforcing gambling contracts, repealing the Gaming Act 1845 rule that treated wagers as void.
A gambling contract can still fail on other grounds. Where the operator is unlicensed, illegality under general contract principles can defeat enforcement, so section 335 does not rescue a bet placed outside the Gambling Commission’s licensing regime.
Insurable interest is the line UK law draws between insurance and a wager. The Life Assurance Act 1774 bars life policies taken out by anyone without a genuine interest in the life insured, which is why an insurance policy is a valid aleatory contract and a bet on a stranger’s death is not.
In the United States, wagering contracts are generally unenforceable as contrary to public policy unless a statute authorises the activity, such as state-licensed gaming or regulated sports betting. Insurance and annuity contracts are enforceable in every state, subject to state insurance codes.
Louisiana is the one US state that defines the category by statute. Article 1912 of the Louisiana Civil Code provides that a contract is aleatory when, by its nature or the parties’ intent, performance or the extent of performance depends on an uncertain event.
Under EU and Nordic frameworks, aleatory contracts are a named civil law category rather than a common law description. The French Civil Code classifies gambling, insurance, and life annuities as contrats aléatoires but denies any court action for the recovery of a gambling debt.
German law treats contracts concluded in breach of gambling prohibitions as void. Belgian law takes the opposite position on imbalance: an aleatory contract cannot be set aside merely because performance proved grossly unequal, since both parties accepted that risk at the outset.
In Sweden, commercial gambling operates under the Gambling Act (Spellag 2018:1138) and is supervised by Spelinspektionen, the Swedish Gambling Authority.
Section 33 of the Swedish Contracts Act allows a gambling agreement to be set aside where enforcing it would be contrary to good faith and honour. The Swedish Supreme Court applied that route in 2024 to void a contract with a compulsive gambler and order repayment of net losses.
Insurance is the one aleatory contract type all three systems regulate rather than merely enforce.
Insurance Regulation
Insurance regulations are crucial for the enforceability and operation of insurance-related aleatory contracts, ensuring fairness, transparency, and protection for both insurer and insured.
Regulatory bodies like the National Association of Insurance Commissioners (NAIC) in the U.S. and the UK’s Financial Conduct Authority (FCA) set and enforce standards for licensing, policy terms, claims handling, and consumer protection.
In the UK, prudential standards including solvency sit with the Prudential Regulation Authority, part of the Bank of England, while conduct supervision is the FCA’s remit. These regulations ensure ethical operation and adequate financial reserves.
Across the EU and the Nordics, insurers are supervised nationally under harmonised rules, with EIOPA coordinating the Solvency II prudential regime and the Insurance Distribution Directive setting conduct and disclosure standards.
Clear disclosure of policy terms is mandated, helping consumers understand coverage, exclusions, and conditions, preventing disputes and enhancing trust.
Regulations also provide for dispute resolution and consumer rights, allowing policyholders to seek redress for unfair claims handling. Adhering to these standards strengthens the enforceability of insurance contracts, promoting stability and confidence in the market.
Consumer Protection and Legal Rights
Consumers entering aleatory contracts, like insurance policies or gambling agreements, have legal rights to protect them from unfair practices and ensure equitable treatment.
These rights include access to clear and transparent contract terms, fair and prompt claims handling, and dispute resolution mechanisms. Regulatory bodies enforce these rights by requiring strict disclosure, ensuring consumers understand the risks, benefits, and obligations of the contract.
Protection measures include oversight by insurance commissions and gambling authorities, monitoring industry practices, and enforcing compliance. Consumer protection laws mandate fair marketing and prohibit deceptive advertising.
Ombudsman services, consumer hotlines, and legal aid assist in resolving disputes and seeking redress. These measures ensure fair treatment and foster trust in aleatory contracts.
Contract Drafting and Conditions
To draft legally enforceable aleatory contracts, clearly outline terms, specify uncertain events triggering obligations, define each party’s rights and responsibilities, and state the consideration exchanged. Ensure clarity to prevent disputes, and include provisions for claims handling, dispute resolution, and contract termination.
Common conditions include definitions of triggering events, detailed coverage and exclusions, premium payment processes, dispute resolution methods like arbitration or mediation, and governing law and jurisdiction.
Ensure all terms are transparent and easily understandable to meet consumer protection regulations. This ensures enforceability and protects all parties’ interests.

Challenges and Complexities
Aleatory contracts present challenges due to their reliance on uncertain future events. Predicting these events is difficult, leading to variability in obligations and benefits, requiring comprehensive risk assessment and sophisticated actuarial analysis.
Clear communication and documentation are essential to ensure both parties understand and accept the risks and terms.
Industry-specific challenges add complexity. In insurance, accurately assessing risk and setting competitive premiums is difficult. In gambling, regulatory compliance and responsible gaming practices are critical.
Managing uncontrollable events, like natural disasters or market crashes, requires detailed contingency planning and navigating regulatory requirements. These factors highlight the need for careful drafting, risk management, and regulatory adherence in aleatory contracts.
Predictability vs Unpredictability
Aleatory contracts balance predictability and unpredictability, addressing uncertain future events. This unpredictability is mitigated by statistical models, historical data, and risk assessments to predict potential outcomes and financial impacts.
Insurers use actuarial science to set premiums based on event likelihoods, balancing risk and payments.
The balance between predictability and unpredictability poses challenges. Insurers must predict risks to maintain solvency, but inherent uncertainty can lead to unexpected losses. Policyholders face uncertainty about benefits.
In gambling, bettors deal with unpredictable outcomes, while operators manage high payout risks. Effective contract design, clear communication, and disciplined financial planning are essential to manage these challenges.
Dealing with Uncontrollable Events
Aleatory contracts are specifically designed to address uncontrollable events and unforeseen circumstances by defining the obligations and benefits contingent upon the occurrence of these events.
These contracts explicitly outline what constitutes an uncontrollable event, such as natural disasters, accidents, or sudden market changes, and detail the responses and responsibilities of the parties involved.
For example, in insurance contracts, clauses stipulate the conditions under which claims can be made and the process for compensation if the insured event occurs. This structure allows parties to manage and mitigate the financial impact of such events through predetermined terms and conditions.
The implications for contract enforcement and risk management are significant. By clearly delineating the terms related to uncontrollable events, aleatory contracts provide a legal framework that ensures enforceability even in the face of uncertainty.
This reduces the potential for disputes and enhances predictability in otherwise unpredictable situations. Effective risk management is achieved by transferring the financial burden of uncontrollable events from one party to another, typically in exchange for a premium or fee.
This transfer of risk helps individuals and businesses protect themselves against substantial financial losses, promoting stability and security despite the inherent unpredictability of the events covered by the contract.
Drafting and Managing Aleatory Contracts
Drafting and managing aleatory contracts can be a challenging and time-consuming endeavour due to their inherent complexity and the need for precise language to address uncertain future events.
The unpredictability of these contracts requires meticulous attention to detail in outlining the conditions, responsibilities, and potential outcomes for each party. Ensuring compliance with regulatory standards, maintaining clarity in terms, and accurately assessing and documenting risks are essential but intricate tasks.
The dynamic nature of the risks involved and the necessity to frequently update contract terms to reflect changing circumstances further complicate the process.
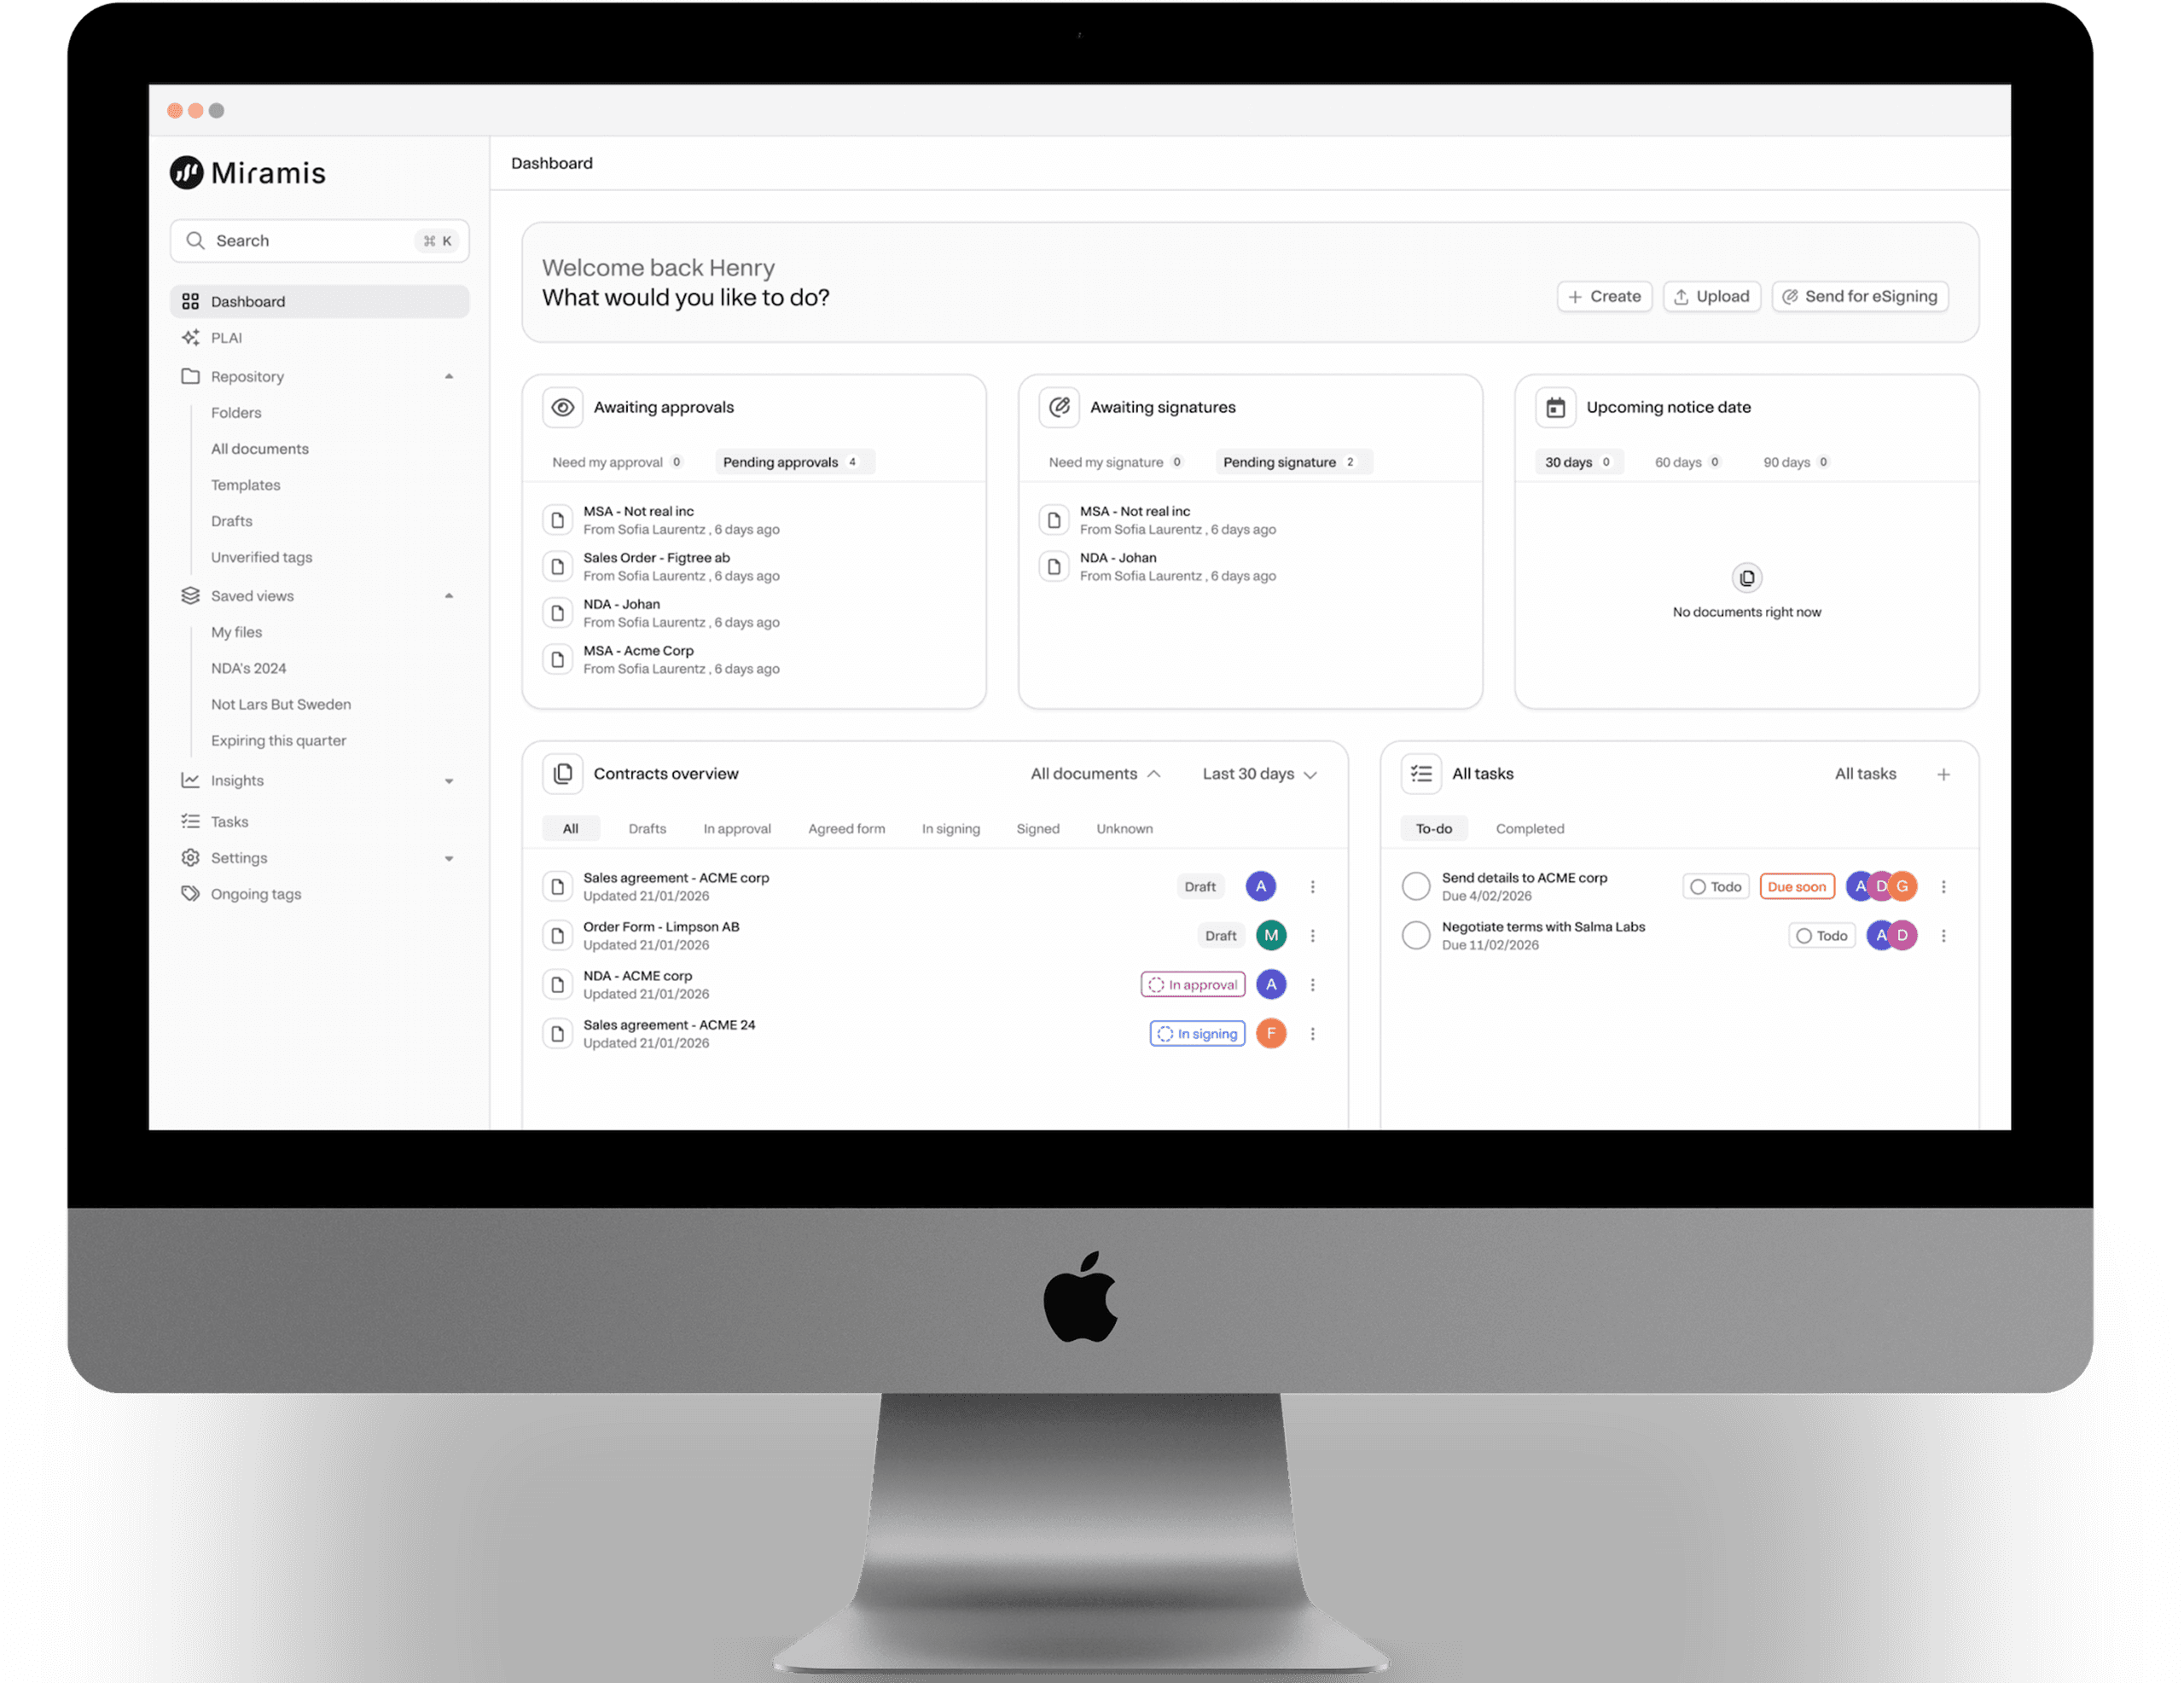
To address these challenges, various solutions can streamline and simplify the management of aleatory contracts. One effective approach is the use of contract lifecycle management (CLM) software, which can automate and organise many aspects of contract creation, execution, and monitoring.
Such software ensures that all necessary elements are included, compliance requirements are met, and updates are managed efficiently, significantly reducing the manual effort and time required.
Platforms like Miramis (formerly Pocketlaw), an AI-native CLM platform, apply that approach directly to aleatory contracts. The platform simplifies drafting and management by integrating every stage of contract management in one place, from creation through storage and obligation tracking.
Pre-approved templates and playbook-based guardrails help teams handle the complexity of aleatory terms without drafting each agreement from scratch. The platform ensures that all contractual obligations are clear, compliant, and up-to-date, minimising the risk of errors and omissions.
Disclaimer:
Please note: Miramis is not a substitute for an attorney or law firm. So, should you have any legal questions on the content of this page, please get in touch with a qualified legal professional.
Related articles

10 ChatGPT Use Cases for Lawyers & Legal Teams
Discover how ChatGPT enhances legal research, drafting, and compliance while understanding its limitations and the best ways to use AI effectively in legal practice.

Executed Contracts: From Signing to Management
Executed contracts are legally binding agreements signed by all parties, confirming terms and ensuring smooth business transactions and partnerships.

What Is Discharge of Contract in Contract Law?
Discharge of contract releases both parties from their obligations. Learn the five routes, how UK, US, and EU law differ, and what survives after discharge.